



Your credit does not have to be perfect. You do need a number, a plan, and the discipline to protect it
1. Your credit does not have to be perfect
This is the myth I hear most often, and it stops so many families before they even begin: “My credit is not perfect, so I cannot buy.” You can. Perfect is not the standard.
With a Federal Housing Administration (FHA) loan, buyers can be approved from about a 580 credit score with 3.5% down. Every lender and every file is different, so that number is a starting point for a conversation — not a promise. What lenders look at most closely is the pattern behind the score:
Payments on time. A history of paying on time tells a lender you will do the same with a mortgage.
Your debts compared with your income. This is your debt-to-income ratio, and it helps determine how much house fits your real life.
No new credit right before you buy. New accounts and hard inquiries can move your score and raise questions at the worst moment.
Three steps you can start today
Check your credit — it is free. You cannot fix what you have not seen, and many reports contain errors worth disputing.
Pay every account on time. Set reminders or autopay for at least the minimum. Consistency is what builds the pattern lenders trust.
Do not close your oldest cards. The age of your credit history helps your score. Keep those older accounts open, even if you use them rarely.
2. Pre-approval is your first real step
Before you fall in love with a house, fall in love with your number. That was the heart of Episode 7, and I say it to every buyer I work with.
A pre-approval is when a lender reviews your income, your credit, and your debts — with real documents — and tells you, in writing, how much you can borrow. It is free, it does not commit you to anything, and it changes how sellers see you. In a competitive conversation, a buyer with a letter in hand is a serious buyer. A buyer without one is a hope.
Pre-approval is not pre-qualification
Pre-qualification is an estimate based on what you tell a lender. It is a useful first chat, but it is not verified.
Pre-approval is a real analysis, with documents. Sellers take only the second one seriously — and so should you.
Knowing your number also protects your heart and your budget. You shop inside what fits, you negotiate with confidence, and you do not waste weekends touring homes that were never in range. If you want to know your number, message me the word PRE-APPROVED and I will connect you with lenders who speak your language and explain every step clearly, in English or in Spanish.
3. Protect your pre-approval until you have the keys
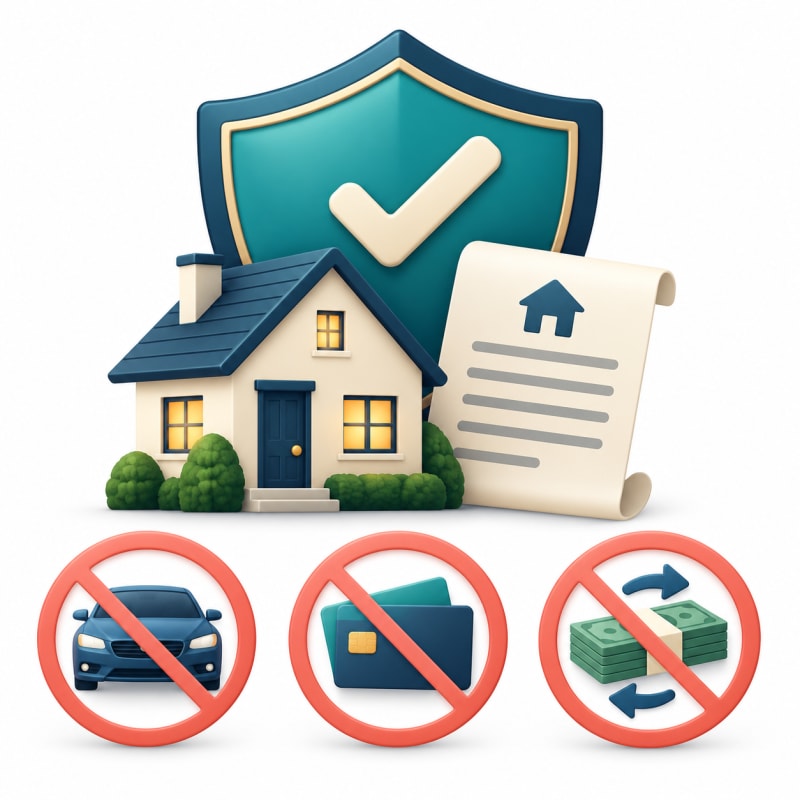
Getting pre-approved feels like the finish line. It is not — it is the starting line with a deadline. That was Episode 8, and it may be the most important of the three, because lenders review your file again before closing. Until the keys are in your hand, your approval can still change.
Three things not to do after your pre-approval
Do not buy a car. A new auto loan changes your debt-to-income ratio and your monthly obligations overnight.
Do not open new credit. No new cards, no store financing, no “buy now, pay later” for furniture for the new house — not yet.
Do not move large amounts of money. Large, undocumented deposits create paperwork problems and delays. If money needs to move, ask your lender first and keep the paper trail.
I know it is tempting. You are imagining the new living room, the new driveway, the new life. Hold that picture — and wait. After closing, buy what you want. Before closing, protect the loan that gets you home.
Your three-step checklist
Step | What to do | Why it matters |
1. Credit | Check it free, pay on time, keep old cards open | Builds the pattern lenders trust |
2. Pre-approval | Get your number in writing, with documents | Sellers take you seriously |
3. Protect it | No car, no new credit, no big money moves | Keeps your closing on track |
Ready to find your number?
If October’s three steps left you with one clear next move, it is this: find out what you can actually do, with real numbers, before you guess. A pre-approval conversation is free and comes with no commitment — just clarity.

GRISELDA SANCHEZ
📍 Serving Culpeper and surrounding areas
📞 Call/Text: 571-308-3626
📧 Email: griselda.sanchez@nhabitco.com
🌐 Website: www.griselda-sanchez.com
Follow for tips, listings, and updates:
📸 Instagram: @griselda.sanchez_realtor_va
📘 Facebook: Griselda Sanchez, VA Realtor
